

Food consumption in Italy is still burdened by high prices that reduce the shopping cart to the bare essentials. Revenue grows, sold volumes decrease. However, marked trends emerge in this scenario, as summarized by the 15th edition of the Immagino Observatory, which captures the scenario as of December 2023.
The GS1 Italy report, established in 2016, analyzes labels (with more than one hundred variables) of over 139 thousand products sold in supermarkets and hypermarkets and integrates the analysis with consumption and sales data collected by NielsenIQ.
The meta-product of the Immagino Observatory
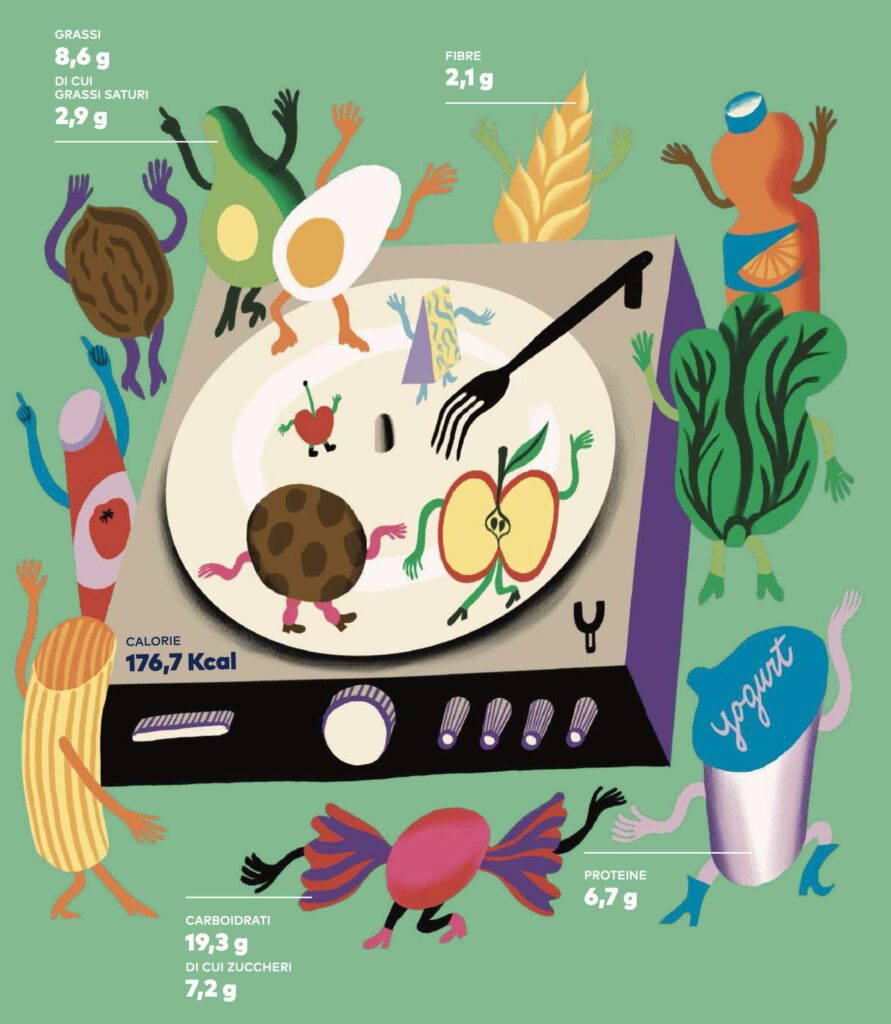
The meta-product is a synthetic statistical indicator, developed by the Immagino Observatory, which creates an average nutritional label of food consumption in Italy.
The average nutritional table is characterized, in the second half of 2023, by an increase in proteins and a reduction in sugars, with fats and carbohydrates stable. The latter remain the primary macronutrient (19.3%). The simple sugars sub-component decreases, thanks to lower consumption of sugar, cola, fresh milk, nectars and similar, multipack ice creams, orange soda, 100% juices, tea-based drinks e fruit-based drinks 30-99%, variably generous in sugar content, as seen.
Fats, in second place, are stable (8.6%). Less extra virgin olive oil, olive oil, tuna in oil, seed oil, fresh milk, shelled nuts, multipack ice creams, sausages, fresh ready-made sauces and cooking-use stretched pasta are consumed.
More proteins and fibers
Proteins are growing again (+1.3%, to 6.7%), thanks to greater consumption of hen eggs, sports foods, grana and similar cheeses, traditional biscuits, shelled nuts, strained Greek yogurt/skyr, whole yogurt, fermented milk/kefir, tomato puree and sweet spreads.
Dietary fibers slightly increasing (2.1%, +0.5%), finally, thanks to the consumption of sports foods, traditional biscuits, shelled nuts, dried legumes, tomato puree, pastries and milk substitutes.
Made in Italy, only DOPs are saved
The label appeal to Italian-ness loses appeal. For over 26 thousand products identified as such, 2023 ended with a -4.5% drop in volumes sold, against a +7.4% increase in turnover. Price inflation has cut purchases of foods prominently labeled with
– Italian flag (-4.1% volume sales compared to 2022), especially bad for multipack ice creams, fresh milk and frozen pizzeria products
– 100% Italian (-5.3%, especially for fresh milk, multipack ice creams and alcoholic beers)
– product made in Italy (-7%, particularly for Easter eggs, frozen breaded prepared fish and Italian DOC and DOCG wines).
Protected geographical indications are also yielding. Only the DOPs are saved. In particular among the top three protected denominations
– the 2,291 DOC wines are first in number. In 2023 they produced over 533 million euros in sales, +3.2% in value and -3.8% in volume
– the 1,328 DOP products are instead first in sales value, almost 716 million euros. In 2023 they recorded the highest growth rate in value (+9.1%) and – unique case in the basket of Italian-ness – also an increase of +1.6% in volume,
– the 992 DOCG wines suffered a volume sales decline of -3.6%. Thanks to price increases, the turnover still grew by +1.7%, up to over 298 million euros.
– Igp and Igt finally experienced a collapse in numerical sales (-5%) and a minimal increase in turnover, +1.7% to 298 million euros in 2023.
Regional origin
Regional origin is indicated on 10,420 products. As usual, in 2023 sales increased in value (+5.2%, up to over 3 billion euros) and decreased in volume (-3.7%).
The most relevant trend belongs to Molise, followed by Puglia, Sardinia, Aosta Valley, and Basilicata, all regions with double-digit growth.
Only five regions closed 2023 with a positive sign also in volumes sold: Molise, Basilicata, and Aosta Valley increased them, while Abruzzo and Puglia kept them generally stable.
The top five ranked regions
The top five is composed as follows:
– Trentino-Alto Adige still at the top of the ranking. The volume sales decline (-2.7%) is influenced by classic sparkling wine, diced cold cuts, apples, and durum wheat pasta
– Sicily confirms the second position, with 1,194 products. In 2023 it recorded a trend of +2.4% in value and -6.7% in volumes, penalized by the negative trend of oranges, multipack ice creams, mozzarella, and alcoholic beers
– Piedmont, holding third place, with a +3.8% growth in value and a -7.1% drop in volume sales, especially in third beef processing, other traditional fresh cheeses, and DOC and DOCG wines
– Emilia-Romagna, with an increase in value sales of +8.4% and a contraction in volume sales of -4%. Wines (Igp, Igt, Doc and Docg), egg pasta, and honey were among the categories most in decline
– Veneto, with 794 products generating 286 million euros (+6%) and also overall maintaining volume (-0.5%). The decline in Doc and Docg wines, fresh milk, and nectars is partly offset by the positive performance of tomato puree.
‘Free from’
The free from basket – over 14 thousand foods whose labels boast the absence of certain ingredients or nutrients – are worth a total turnover of 8.1 billion euros, up +9.7%. Conversely, volumes closed the year with a negative trend (-3.5%).
Among the monitored claims, five have also increased sales volumes, as is now customary, well below the revenue increase. In order of market share, they are
– 'Low fat', stable with +0.4% in volume (+11.5% turnover). Driving Greek strained yogurt/skyr, traditional biscuits, turkey and UHT milk.
– 'Low sugar', +1.9% (+18.3% in value). Among the brightest categories, jams and fruit-based spreads, traditional cookies, preserved fruit, fruit-based drinks 30-99%, bases and cola.
– 'Without added sugars', +5.4% (+18.5% in value). Very good jams and fruit-based spreads, preserved fruit, traditional cookies and fruit-based drinks 30-99%.
– 'Without hydrogenated fats' +1.7% (+15.2% turnover). Sales of healthy and traditional cookies, pastries, ready cakes and margarine are growing.
– 'Without aspartame', +5.1% (+10.8% in value). The synthetic sweetener – considered by IARC a possible carcinogen – is increasingly often rejected by consumers. Leading are sweeteners, orange soda and cola.
‘Rich in’
The 11 thousand foods naturally rich or enriched with beneficial components have increased turnover in 2023 by +10%. Volumes sold instead decreased by -2.2%, with only two exceptions:
– 'lactic ferments', remained substantially stable, with sales volumes at +0.3%, especially thanks to fermented milk/kefir, whole yogurt and crescenza cheese,
– 'proteins', the main claim for business turnover (+12.8%, up to 1.88 billion euros) in the 'rich in' basket has grown in volume by +1.2%. Very good fresh and UHT milk, hard cheeses and similar, bases and sports nutrition.
Foods for food intolerances
The almost 11 thousand products offered as suitable for people with food intolerances are also burdened by price increases. Turnover grows overall by +6.2% (to over 4.7 billion euros) but volume sales decrease by -3.9%.
The negative series regarding volume sales concerns
– 'gluten free' (-4.4%),
– 'lactose free' (-1.3%),
– 'gluten free with AIC logo', Italian Celiac Association (-7.3%),
– 'milk free' (-5.1%),
– 'yeast free' (-3.1%).
The claim 'egg free' is an exception. The smallest segment of the basket has in fact also grown in volume (+3.6%), especially thanks to fresh unfilled pasta, fresh gluten-free pasta, gluten-free pasta and healthy biscuits.
Lifestyle at the table
Among the five claims which identify products consistent with a specific lifestyle, overall the gap between revenue increase (+8.7%) and sales volume decrease (-2.4%) reappears.
Three references to the absence (total or partial) of ingredients of animal origin,
– 'veg', which is worth 24 billion euros, records +10.4% in sales value and -1.6% in volume trend. Very poor, in volume, ready first courses, whole and portioned table cheeses, industrial fresh cheeses, sliced cheeses and multipack ice creams
– 'vegetarian', with revenue at +9% and volumes at -3.1%, declines in the same categories of the 'veg' claim
– 'vegan', finally, increases sales in value (+11.9%) and volume (+0.2%). Good for jams and fruit-based spreads as well as natural vegetable/fruit frozen products.
Organic
The 'bio' claim on 8,200 references in 2023 develops more than 1.2 billion euros in sales, +2.8%. Sales volumes instead fall by -5.1%. Particularly bad are fresh milk, fourth range vegetables, rice cakes, whole wheat/spelt/kamut/legume-based pasta and even chicken eggs.
Organic foods, it should be remembered, however, that they are often purchased in farmers' markets and specialty stores, sales channels not yet considered in the Immagino Observatory.
Kosher and halal
The same consideration applies to foods certified as kosher or halal, mainly available in dedicated commercial outlets. In the supermarket and hypermarket channel, the two claims related to religious prescriptions show different trends:
– 'kosher', suitable for the Jewish religion, appears on 1,710 products and grows in value by +10.3%, up to over 921 million euros. In volume, however, it decreases by -1.4%, mainly due to extra virgin olive oil, ground coffee, jams and fruit-based spreads, pralines and chocolates,
– 'halal', present on 521 products, experiences a successful 2023, helped by the increase of Muslim foreigners from Bangladesh and Afghanistan. Growth is +16.7% in value (for a turnover of over 269 million euros) and +5.9% in volume, especially thanks to durum wheat pasta, grana cheese and similar products, and natural vegetable/fruit frozen items.
‘Beneficial’ ingredients
Among the foods with clear labeling of a ‘beneficial’ ingredient, the general contrast between increasing revenue and declining sales volume is fully confirmed.
Traditional. Seven claims recall the most loved ‘traditional’ products in Italy. Cocoa, hazelnut, lemon, vanilla, pistachio, walnuts and caramel. The decline in sales volume is widespread and double-digit in three cases: hazelnut (-12.9%), vanilla (-14.6%) and caramel (-12.9%).
Superfruit. Same trend for the seven monitored superfruits, with a sales volume drop of -4.4%.
Almond and blueberry lose sales volume respectively by -7.4% and -7.9%.
Three exceptions. Sales volume grows for
– cashews, +5.2%,
– avocado, +24.1%, marking growth that in recent years appears unstoppable,
– coconut water, essentially stable at +0.6%.
Rice and oats, the exceptions
In the group of super grains and flours, oats, rice flour and rice oil are the only ones to boast an increase in sales volume: +4.1%, +1.6%, and +5.3%.
Of the two sweeteners monitored, sales volume plummets by -7.5% for brown sugar and remains essentially stable for stevia, -0.1%, despite revenue increasing by +5.6%.
Among the seeds, despite an overall increase in value sales (+6.8%) and a decrease in volume sales (-4.5%), there is a sharp reduction in the number of purchases of pumpkin seeds (-9.2%) and hemp seeds (-11.9%).
Spices recorded a negative performance in 2023 especially in volume (-10.5%) but also in value (-2%). For the latter, the collapse is -10% for ginger, -17% for turmeric and -8.1% for cinnamon.
Superfood
The superfoods, the last group of beneficial ingredients monitored by Osservatorio Immagino, are also aligned with the trend caused by price increases: sales value increased by +2.8% while volumes decreased by -2.7%.
‘Royal jelly’ is the claim with the highest turnover: 20.3 million euros generated by 48 references. Sales grow in value (+6.8%) and, albeit slightly, also in volume (+0.8%).
‘Peanut butter’ It is in second place for turnover, 18.4 million euros from just 50 products. Sales growth is double-digit both in value (+15.7%) and volume (10.7%). Sweet spreads, milk-based drinks and wafers perform well.
'Edamame', with 7.5 million euros in turnover and 28 products on shelves, will lose -7.9% in value and -13.8% in volume in 2023.
‘Goji’ and ‘Acai’ plummet with volume sales reduced by -25.9% and -41% respectively.
‘Matcha’, ‘spirulina’ and ‘tahina’ hold instead with quantitative sales of +0.7%, +4.1% and +2.7%.
Processing method
‘Artisanal’ is countertrend compared to other claims on the processing method. Found on 752 products, it increased sales in value by +21.6% (for a turnover of 143 million euros) and in volume by 17.1%, mainly thanks to frozen pizza.
‘Drying’ is the only other claim in the group to hold. Typical of dry pasta, the claim shows sales growth of +7.8% in value and +3.1%.
Very bad volume sales of ‘handmade’ (-13.2%), ‘unfiltered’ (-17.1%) and ‘smoking’ (-10.3%). Regarding the latter claim, we recall the recent decision of the European Commission to reject the renewal of the authorization of smoking aromas as genotoxic, but retaining them in foods for a further five years.
Falling also the volume sales of products with the claim ‘cold extracted’, essentially extra virgin olive oil. Price increases raise turnover by +31.5% but reduce volume sales by -3.1%.
Food consistency
The consistency of the food (the texture) represents an attraction for consumers. The related claims appear on 7,792 references, which in 2023 generated over 1.4 billion euros in sales. The sales trend is positive in value (+10.4%) but negative in volume (-4.1%).
Among the 11 claims monitored, only two show positive signs in volume sales:
– 'soft' with +1.3% (+14.2% in value) is driven by sandwich bread, loaf bread, sandwich bread, and cold cuts. It is worth a turnover of 532 million euros,
– 'rough' with +0.9% (+13.7% in value) totals a turnover of 206 million euros. Very good are semolina pasta and whole wheat pasta, spelled and kamut, as well as legumes.
Marta Strinati
Notes
(1) Immagino Observatory 2024.1. GS1 Italy https://servizi.gs1it.org/osservatori/osservatorio-immagino-15/
Professional journalist since January 1995, she has worked for newspapers (Il Messaggero, Paese Sera, La Stampa) and magazines (NumeroUno, Il Salvagente). Author of journalistic investigations on food, she published the volume 'Reading labels to know what we eat.'


